Quick support from trusted insurance professionals Call +1 713-777-2886 today!
Quick professional support Call +1 713-777-2886 today!
Quick professional support Call +1 713-777-2886 today!
Table of Content
Title
Let AZ Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Do I Need Commercial Auto Insurance for My Business in Texas?
Do I Need Commercial Auto Insurance for My Business in Texas?
Do I Need Commercial Auto Insurance for My Business in Texas?
Do I Need Commercial Auto Insurance for My Business in Texas?
Do I Need Commercial Auto Insurance for My Business in Texas?
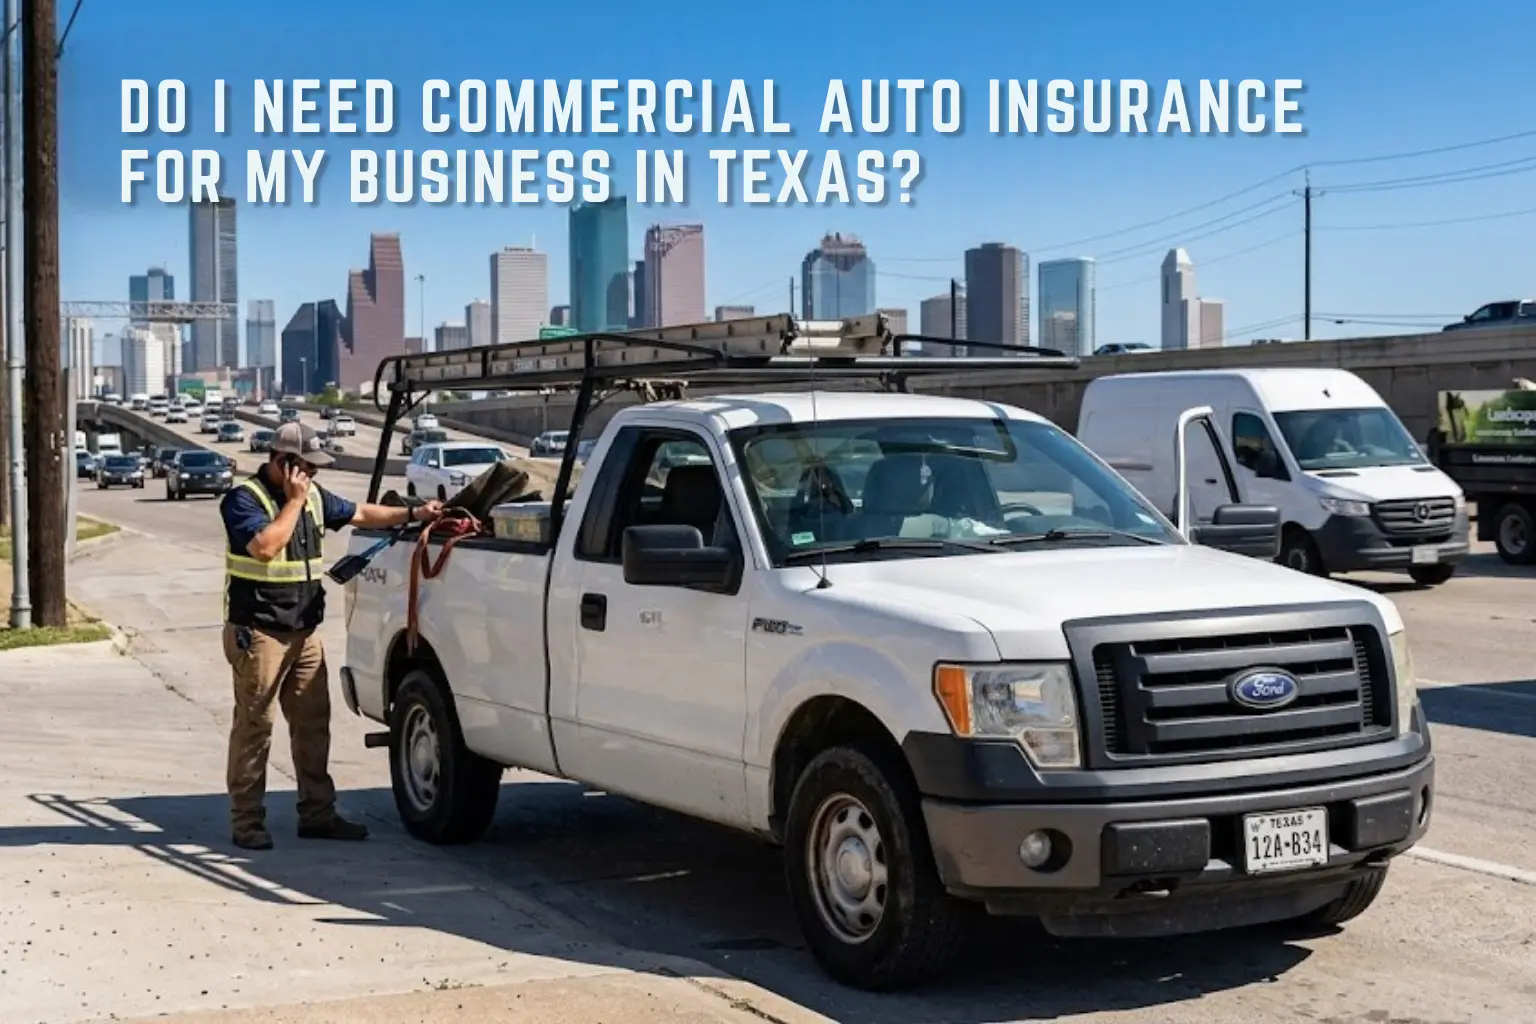
If you're a contractor, tradesperson, or small business owner in Houston, you probably use a vehicle every single day for work - hauling tools to a job site, transporting equipment, picking up materials, or moving your crew from one location to the next. And if that vehicle is only covered by a personal auto policy, you may have a serious coverage gap you don't even know about.
The question isn't really whether you should look into commercial auto insurance. The question is: are you already operating without it - and what happens if something goes wrong?
Personal Auto Insurance vs. Commercial Auto Insurance: What's the Difference?
This is the most important thing to understand: personal auto insurance is designed for personal use. The moment you use your vehicle for business purposes - even occasionally - your personal policy may deny a claim.
Personal Auto Policy | Commercial Auto Policy |
Covers personal errands and commuting | Covers business use, job site travel, hauling equipment |
Lower liability limits | Higher liability limits suited for business risk |
Does NOT cover employees driving your vehicle | Covers employees and additional listed drivers |
Does NOT cover tools or cargo in the vehicle | Can include cargo and equipment coverage |
May deny claims if vehicle was used for work | Built specifically for work-related incidents |
Lower premium | Higher premium - but far better protection |
Which Houston Businesses and Trades Need Commercial Auto Insurance?
If any of the following sounds like you, you need a commercial auto policy - not a personal one:
General contractors and subcontractors driving to job sites
Plumbers, electricians, HVAC technicians, and roofers hauling tools and equipment
Landscapers and lawn care companies with trucks or trailers
Painters, handymen, and remodelers transporting supplies
Delivery drivers or couriers using a personal vehicle for business
Mobile businesses - food trucks, mobile detailing, mobile pet grooming
Real estate agents and property managers driving clients or visiting properties
Any business where employees drive a company-owned or personally-owned vehicle for work
A good rule of thumb: if the vehicle helps you make money, it needs to be covered by a commercial policy.
What Does Commercial Auto Insurance Cover?
A commercial auto policy covers the same fundamental risks as personal auto - liability, collision, comprehensive - but with higher limits and broader protection built for business use. Here's a breakdown:
Liability Coverage
Pays for injuries and property damage you or your employees cause to others while driving for work. Commercial policies carry much higher limits than personal policies - critical when you're operating a work truck on a busy Houston highway.
Collision & Comprehensive
Covers physical damage to your business vehicle - whether from an accident, theft, hail, or vandalism. In Houston, where hail season and flooding are real annual risks, this coverage is especially valuable for contractors who depend on their truck every day.
Hired & Non-Owned Auto Coverage
This is one of the most overlooked coverages for small businesses. If your employees use their personal vehicles for work - running to pick up supplies, making deliveries, driving to a client - and they get into an accident, your business could be liable. Hired & Non-Owned Auto coverage protects you in those situations.
Uninsured/Underinsured Motorist Coverage
With roughly 1 in 5 Texas drivers uninsured, this is not optional for businesses. If one of your drivers gets hit by an uninsured motorist on the way to a job site, UM/UIM coverage ensures the business doesn't absorb the loss.
Commercial Auto Insurance Requirements in Texas
Texas requires commercial vehicles to carry minimum liability coverage - but the minimums vary based on the type of vehicle and how it's used. Here's a general guide:
Vehicle / Business Type | Typical Min. Liability | Notes |
Light commercial vehicles (contractor trucks, vans) | $30,000 / $60,000 / $25,000 | Same as personal minimum; higher limits strongly recommended |
Vehicles hauling hazardous materials | $1,000,000+ | Federal requirements apply |
For-hire transportation (TNC, delivery) | Varies by use | Rideshare/delivery apps may require specific endorsements |
Heavy trucks / commercial freight | $300,000 - $750,000+ | Depends on weight class and cargo type |
How Much Does Commercial Auto Insurance Cost in Texas?
Commercial auto premiums vary based on your industry, number of vehicles, driver records, coverage limits, and how the vehicle is used. Here's a general range for small Houston-area trade businesses:
Business Type | Est. Annual Premium (1 Vehicle) |
General contractor / handyman | $1,200 - $2,500/yr |
Plumber / electrician / HVAC tech | $1,500 - $3,000/yr |
Roofer / painter | $2,000 - $4,500/yr |
Landscaper with trailer | $1,800 - $3,500/yr |
Delivery / courier (light vehicle) | $2,500 - $5,000/yr |
*Estimates only. Your actual rate depends on driving history, coverage limits, and vehicle type.
Frequently Asked Questions
Can I just add a business-use endorsement to my personal policy?
Sometimes - for very light business use like occasionally visiting a client. But if you're hauling tools, carrying equipment, or transporting employees, a business-use endorsement typically won't provide enough protection. A dedicated commercial policy is the right solution.
What if my employee gets into an accident driving my truck?
If the truck is on a commercial policy and the employee is listed as a driver, your commercial policy covers the accident. If they were driving and your vehicle only had a personal policy, you could be looking at a denied claim and full out-of-pocket liability.
Does commercial auto cover my tools and equipment in the truck?
Standard commercial auto does not cover tools and equipment - that fall under Inland Marine or commercial property endorsement. However, bundling these coverages together is common and cost-effective. Ask your agent about a combined package.
I'm a sole proprietor with one truck - do I really need this?
Yes - especially as a sole proprietor. You have no corporate structure shielding your personal assets. If you cause an accident while working and your personal policy denies the claim, your savings, home, and future income are all on the table. Commercial auto is one of the most important policies a sole proprietor can carry.
Get Commercial Auto Insurance for Your Houston Business Today
At AZ Insurance Agency, we work with Houston contractors, tradespeople, and small business owners every day. We understand the risks you face on the job - and we know how to build a policy that covers your vehicles, your employees, and your business without overcharging you for coverage you don't need.
Whether you have one work truck or a full fleet, we'll get you a fast, no-pressure quote in English or Spanish. With 15 locations across Houston, we're right where you are.
📍 aztexas.com | 15 Houston Locations | English & Spanish
Frequently Asked Questions
Q: I use my personal truck for work sometimes. Am I covered?
Sometimes is exactly where this goes wrong. A personal auto policy is written on the assumption the vehicle is used for personal driving, and most carry a business use exclusion. Driving to one job site occasionally is often fine; hauling tools and materials, carrying a company name on the door, or making deliveries usually is not. The time you find out is after a claim, which is the worst possible time.
Q: Does my business need commercial auto if the vehicle is in my personal name?
It can, and ownership is not the deciding factor. What matters is how the vehicle is used and who is liable if it is in an accident. A vehicle titled to you but used to run the business can leave both you and the business exposed under a personal policy. Tell us the real usage and we will write it correctly.
Q: What is hired and non owned auto coverage?
It covers your business when someone drives a vehicle the business does not own, including an employee running an errand in their own car or a rented truck for a job. Plenty of Houston businesses have no company vehicles at all and still need this, because the liability lands on the business regardless of whose name is on the title.
Q: Are my tools covered if they are in the truck?
Not by the auto policy, in most cases. Tools and equipment need their own coverage, and it is one of the most common gaps we find on policies bought online, where nobody asked what was in the bed of the truck. It is an easy fix once someone actually asks the question.
Q: Do I need it if my employees drive their own cars?
Very likely, through hired and non owned coverage. Their personal policy is the first line, but it often will not respond to business use, and once it is exhausted the claim comes to the business. This is the single most overlooked exposure for service businesses with no fleet.
Q: Will a client or general contractor ask for proof?
Frequently, and often with specific limits written into the contract. Send us the contract language rather than a summary of it, because the wording a general contractor requires is not always what a standard certificate gives them. We would rather read it first than issue a certificate that gets rejected.
If you're a contractor, tradesperson, or small business owner in Houston, you probably use a vehicle every single day for work - hauling tools to a job site, transporting equipment, picking up materials, or moving your crew from one location to the next. And if that vehicle is only covered by a personal auto policy, you may have a serious coverage gap you don't even know about.
The question isn't really whether you should look into commercial auto insurance. The question is: are you already operating without it - and what happens if something goes wrong?
Personal Auto Insurance vs. Commercial Auto Insurance: What's the Difference?
This is the most important thing to understand: personal auto insurance is designed for personal use. The moment you use your vehicle for business purposes - even occasionally - your personal policy may deny a claim.
Personal Auto Policy | Commercial Auto Policy |
Covers personal errands and commuting | Covers business use, job site travel, hauling equipment |
Lower liability limits | Higher liability limits suited for business risk |
Does NOT cover employees driving your vehicle | Covers employees and additional listed drivers |
Does NOT cover tools or cargo in the vehicle | Can include cargo and equipment coverage |
May deny claims if vehicle was used for work | Built specifically for work-related incidents |
Lower premium | Higher premium - but far better protection |
Which Houston Businesses and Trades Need Commercial Auto Insurance?
If any of the following sounds like you, you need a commercial auto policy - not a personal one:
General contractors and subcontractors driving to job sites
Plumbers, electricians, HVAC technicians, and roofers hauling tools and equipment
Landscapers and lawn care companies with trucks or trailers
Painters, handymen, and remodelers transporting supplies
Delivery drivers or couriers using a personal vehicle for business
Mobile businesses - food trucks, mobile detailing, mobile pet grooming
Real estate agents and property managers driving clients or visiting properties
Any business where employees drive a company-owned or personally-owned vehicle for work
A good rule of thumb: if the vehicle helps you make money, it needs to be covered by a commercial policy.
What Does Commercial Auto Insurance Cover?
A commercial auto policy covers the same fundamental risks as personal auto - liability, collision, comprehensive - but with higher limits and broader protection built for business use. Here's a breakdown:
Liability Coverage
Pays for injuries and property damage you or your employees cause to others while driving for work. Commercial policies carry much higher limits than personal policies - critical when you're operating a work truck on a busy Houston highway.
Collision & Comprehensive
Covers physical damage to your business vehicle - whether from an accident, theft, hail, or vandalism. In Houston, where hail season and flooding are real annual risks, this coverage is especially valuable for contractors who depend on their truck every day.
Hired & Non-Owned Auto Coverage
This is one of the most overlooked coverages for small businesses. If your employees use their personal vehicles for work - running to pick up supplies, making deliveries, driving to a client - and they get into an accident, your business could be liable. Hired & Non-Owned Auto coverage protects you in those situations.
Uninsured/Underinsured Motorist Coverage
With roughly 1 in 5 Texas drivers uninsured, this is not optional for businesses. If one of your drivers gets hit by an uninsured motorist on the way to a job site, UM/UIM coverage ensures the business doesn't absorb the loss.
Commercial Auto Insurance Requirements in Texas
Texas requires commercial vehicles to carry minimum liability coverage - but the minimums vary based on the type of vehicle and how it's used. Here's a general guide:
Vehicle / Business Type | Typical Min. Liability | Notes |
Light commercial vehicles (contractor trucks, vans) | $30,000 / $60,000 / $25,000 | Same as personal minimum; higher limits strongly recommended |
Vehicles hauling hazardous materials | $1,000,000+ | Federal requirements apply |
For-hire transportation (TNC, delivery) | Varies by use | Rideshare/delivery apps may require specific endorsements |
Heavy trucks / commercial freight | $300,000 - $750,000+ | Depends on weight class and cargo type |
How Much Does Commercial Auto Insurance Cost in Texas?
Commercial auto premiums vary based on your industry, number of vehicles, driver records, coverage limits, and how the vehicle is used. Here's a general range for small Houston-area trade businesses:
Business Type | Est. Annual Premium (1 Vehicle) |
General contractor / handyman | $1,200 - $2,500/yr |
Plumber / electrician / HVAC tech | $1,500 - $3,000/yr |
Roofer / painter | $2,000 - $4,500/yr |
Landscaper with trailer | $1,800 - $3,500/yr |
Delivery / courier (light vehicle) | $2,500 - $5,000/yr |
*Estimates only. Your actual rate depends on driving history, coverage limits, and vehicle type.
Frequently Asked Questions
Can I just add a business-use endorsement to my personal policy?
Sometimes - for very light business use like occasionally visiting a client. But if you're hauling tools, carrying equipment, or transporting employees, a business-use endorsement typically won't provide enough protection. A dedicated commercial policy is the right solution.
What if my employee gets into an accident driving my truck?
If the truck is on a commercial policy and the employee is listed as a driver, your commercial policy covers the accident. If they were driving and your vehicle only had a personal policy, you could be looking at a denied claim and full out-of-pocket liability.
Does commercial auto cover my tools and equipment in the truck?
Standard commercial auto does not cover tools and equipment - that fall under Inland Marine or commercial property endorsement. However, bundling these coverages together is common and cost-effective. Ask your agent about a combined package.
I'm a sole proprietor with one truck - do I really need this?
Yes - especially as a sole proprietor. You have no corporate structure shielding your personal assets. If you cause an accident while working and your personal policy denies the claim, your savings, home, and future income are all on the table. Commercial auto is one of the most important policies a sole proprietor can carry.
Get Commercial Auto Insurance for Your Houston Business Today
At AZ Insurance Agency, we work with Houston contractors, tradespeople, and small business owners every day. We understand the risks you face on the job - and we know how to build a policy that covers your vehicles, your employees, and your business without overcharging you for coverage you don't need.
Whether you have one work truck or a full fleet, we'll get you a fast, no-pressure quote in English or Spanish. With 15 locations across Houston, we're right where you are.
📍 aztexas.com | 15 Houston Locations | English & Spanish
Frequently Asked Questions
Q: I use my personal truck for work sometimes. Am I covered?
Sometimes is exactly where this goes wrong. A personal auto policy is written on the assumption the vehicle is used for personal driving, and most carry a business use exclusion. Driving to one job site occasionally is often fine; hauling tools and materials, carrying a company name on the door, or making deliveries usually is not. The time you find out is after a claim, which is the worst possible time.
Q: Does my business need commercial auto if the vehicle is in my personal name?
It can, and ownership is not the deciding factor. What matters is how the vehicle is used and who is liable if it is in an accident. A vehicle titled to you but used to run the business can leave both you and the business exposed under a personal policy. Tell us the real usage and we will write it correctly.
Q: What is hired and non owned auto coverage?
It covers your business when someone drives a vehicle the business does not own, including an employee running an errand in their own car or a rented truck for a job. Plenty of Houston businesses have no company vehicles at all and still need this, because the liability lands on the business regardless of whose name is on the title.
Q: Are my tools covered if they are in the truck?
Not by the auto policy, in most cases. Tools and equipment need their own coverage, and it is one of the most common gaps we find on policies bought online, where nobody asked what was in the bed of the truck. It is an easy fix once someone actually asks the question.
Q: Do I need it if my employees drive their own cars?
Very likely, through hired and non owned coverage. Their personal policy is the first line, but it often will not respond to business use, and once it is exhausted the claim comes to the business. This is the single most overlooked exposure for service businesses with no fleet.
Q: Will a client or general contractor ask for proof?
Frequently, and often with specific limits written into the contract. Send us the contract language rather than a summary of it, because the wording a general contractor requires is not always what a standard certificate gives them. We would rather read it first than issue a certificate that gets rejected.
Latest Blogs
Does General Liability Cover Your Own Faulty Workmanship? What Texas Contractors Get Wrong

Buying a Car in Houston? What Insurance You Need Before You Drive Off the Lot

Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open

A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026

A Storm Claim Cannot Raise Your Texas Home Insurance Rate. A Broken Pipe Can.

Your Roof Before the Storm: The Four Things to Check on Your Policy While You Still Can
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto
Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Latest New & Blogs
Latest New & Blogs
Related Blog Posts
Related Blog Posts
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.
A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026
The deadlines your Texas insurer must meet on a storm claim, the appraisal right added for 2026, and what a claim does to your renewal in Fort Bend.
A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026
The deadlines your Texas insurer must meet on a storm claim, the appraisal right added for 2026, and what a claim does to your renewal in Fort Bend.
A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026
The deadlines your Texas insurer must meet on a storm claim, the appraisal right added for 2026, and what a claim does to your renewal in Fort Bend.
A Storm Claim Cannot Raise Your Texas Home Insurance Rate. A Broken Pipe Can.
Texas law protects weather claims from rate increases and nonrenewal. The claims that count against you are the everyday ones. Here is the exact line.
A Storm Claim Cannot Raise Your Texas Home Insurance Rate. A Broken Pipe Can.
Texas law protects weather claims from rate increases and nonrenewal. The claims that count against you are the everyday ones. Here is the exact line.
A Storm Claim Cannot Raise Your Texas Home Insurance Rate. A Broken Pipe Can.
Texas law protects weather claims from rate increases and nonrenewal. The claims that count against you are the everyday ones. Here is the exact line.
Landscaping Insurance in Houston: The Three Gaps Your Personal Policy Leaves Open
The truck, the equipment and the customer's property. Where a personal policy stops paying for a Houston lawn care crew, and what covers each piece.
A Storm Hits Before Your Renewal: The Texas Claim Timeline, and the New Right You Have in 2026
The deadlines your Texas insurer must meet on a storm claim, the appraisal right added for 2026, and what a claim does to your renewal in Fort Bend.