Quick support from trusted insurance professionals Call +1 713-777-2886 today! |
Call +1 713-777-2886
Call +1 713-777-2886
Quick support from insurance professionals Call +1 713-777-2886 today! |
Table of Content
Title
Let AZ Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Climate Risk & Commercial Insurance: What Businesses Need to Know in 2026
Climate Risk & Commercial Insurance: What Businesses Need to Know in 2026
Climate Risk & Commercial Insurance: What Businesses Need to Know in 2026
Climate Risk & Commercial Insurance: What Businesses Need to Know in 2026
Climate Risk & Commercial Insurance: What Businesses Need to Know in 2026
4:58 PM
4:58 PM
Climate-related risks are no longer a future concern-they are a present-day reality for businesses across Texas. From severe storms and flooding to extreme heat and power outages, climate events are changing how commercial insurance works in 2026.
At AZ Insurance, we help business owners understand how climate risk affects coverage, premiums, and protection plans - so you can stay prepared and protected.
How Climate Risk Is Changing Commercial Insurance
Insurance companies are changing policies as weather-related claims continue to rise. Businesses are seeing changes such as:
Higher deductibles for weather-related losses
Higher premiums in high-risk areas
Stricter approval rules for coverage
More focus on risk prevention steps
This makes understanding climate risk commercial insurance more important than ever for business owners. Our team is here to help with understanding coverage options and risk planning.
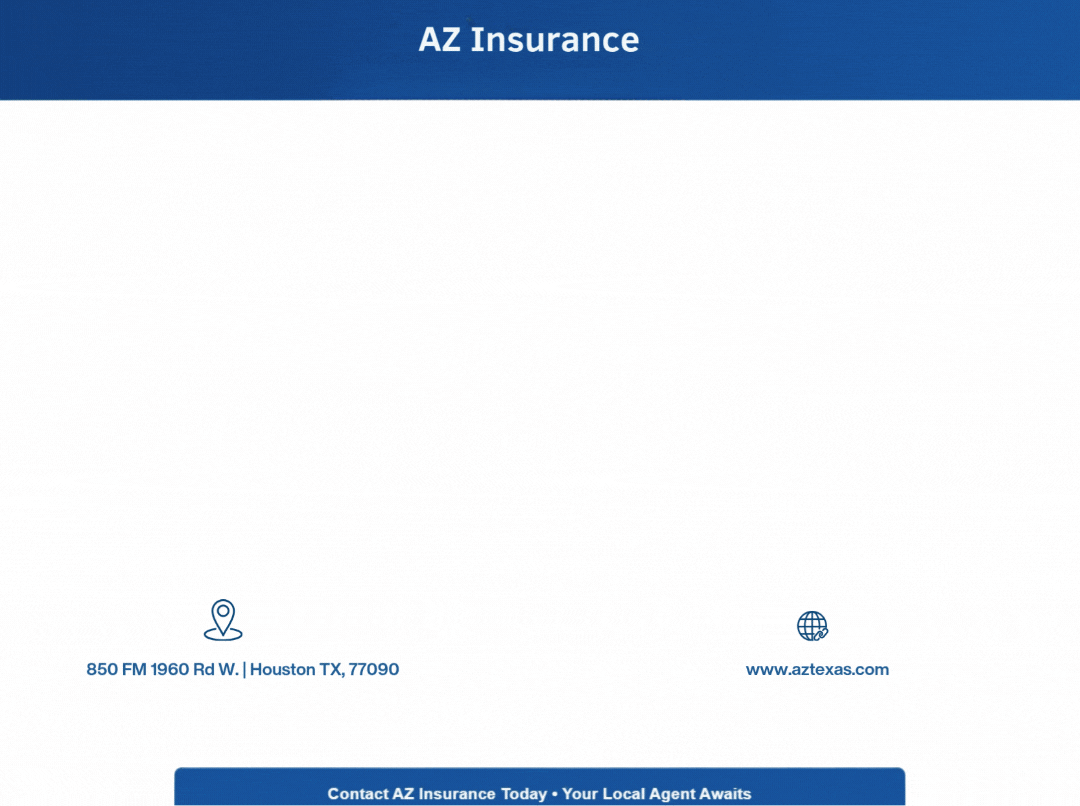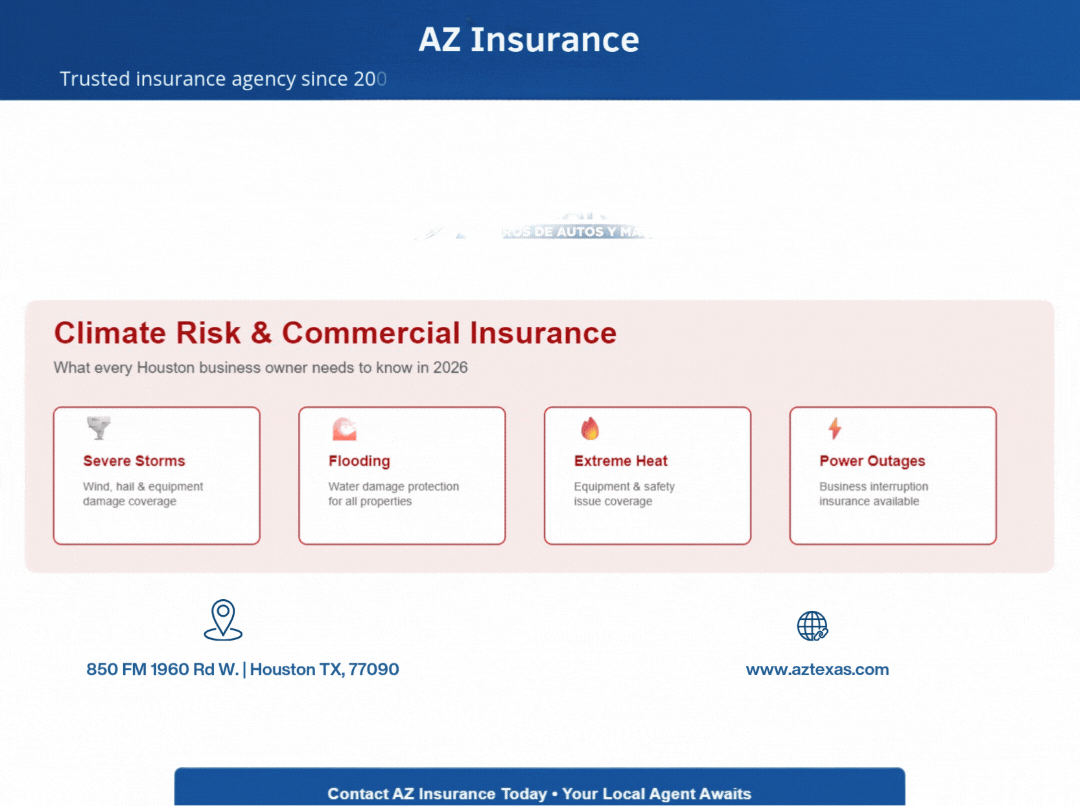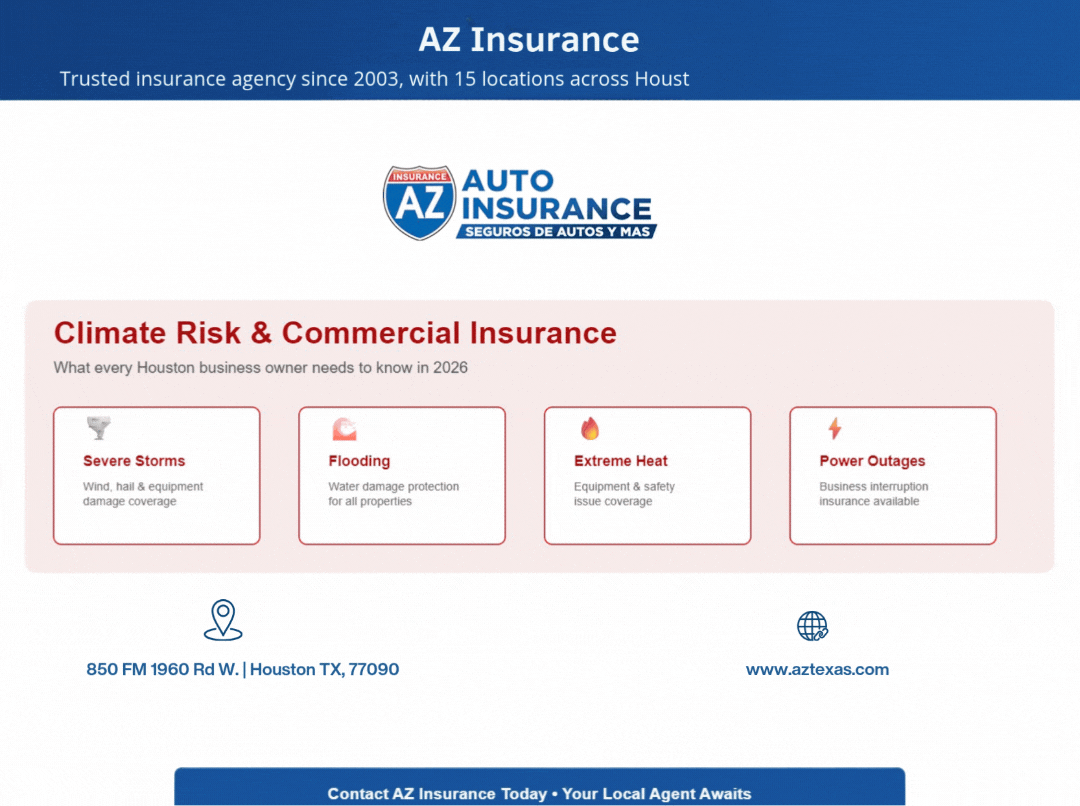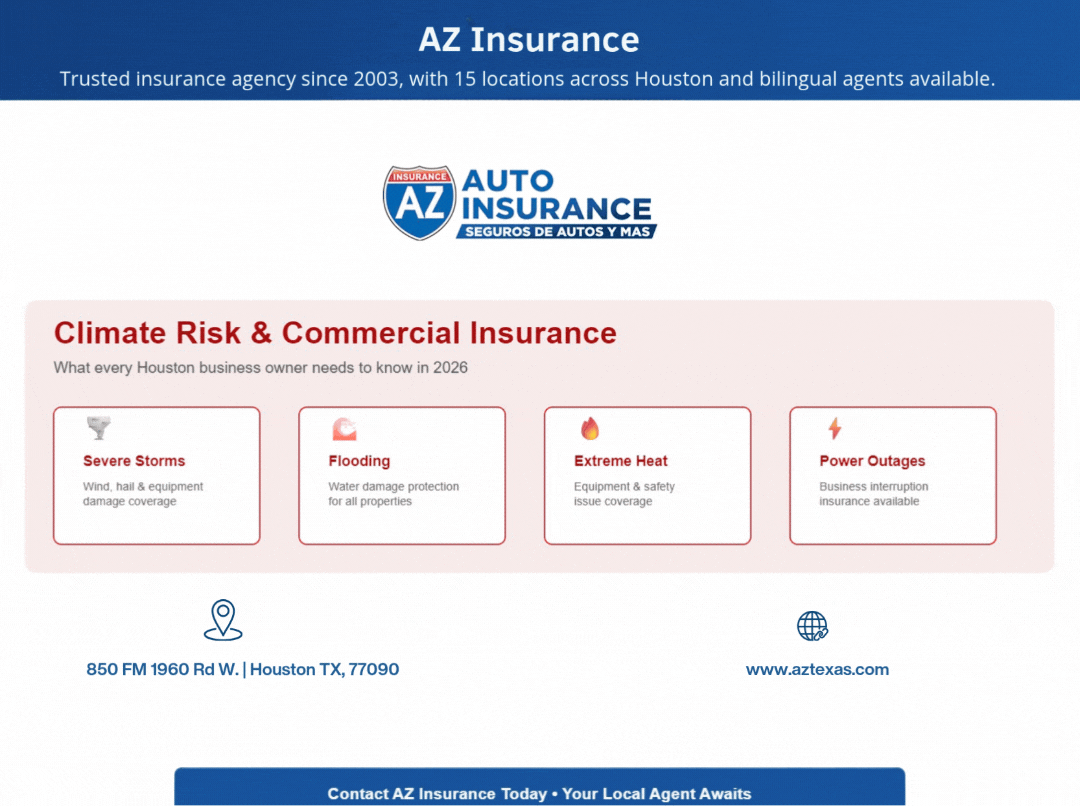
Common Climate-Related Risks Facing Texas Businesses
Texas businesses are especially exposed to climate-related events, including:
🌪 Severe Storms & Wind Damage
Strong winds and hail can damage roofs, signs, and equipment.
🌊 Flooding
Even businesses outside flood zones can face water damage from heavy rain.
🔥 Extreme Heat
Heat waves can lead to equipment breakdown, power issues, and employee safety problems.
⚡ Power Outages
Weather-related outages can stop business operations and cause loss of income.
Without proper coverage, these events can lead to high out-of-pocket costs.
Why Commercial Insurance Coverage Matters More in 2026
The right Texas commercial insurance policy can help protect your business from climate-related losses, including:
Business Interruption Insurance – Helps cover lost income when your business is temporarily closed
Commercial Auto Insurance – Covers damage to business vehicles caused by weather
General Liability Insurance – Protects against claims from third-party property damage
Good coverage helps your business recover faster after unexpected events.
Steps Business Owners Can Take to Reduce Risk
Insurance is only one part of the protection. Businesses can also lower risk by:
Reviewing insurance policies every year
Updating property and equipment values
Following regular safety and maintenance checks
Adding protection systems like drainage, surge protection, and strong roofing
Taking these steps can also help control insurance costs over time.
How to Review Your Policy for Climate Risk
Many businesses think they are fully covered until they face a claim. Reviewing your policy can help you avoid surprises.
Check if flood, wind, or power outage damage is included
Make sure coverage limits match your current property value
See if business interruption coverage includes weather-related closures
Ask your insurer about extra coverage options if needed
A simple review now can prevent big losses later.
Why Businesses Trust AZ Insurance
AZ Insurance has been supporting local businesses and families for years with simple, reliable coverage and real guidance when it matters most. With multiple local offices across Houston, help is always close by when you need it.
Our licensed agents speak multiple languages, so you can get clear answers without confusion. You also deal directly with real people—not automated call centers—so you always get personal support.
We’ve helped thousands of customers find the right coverage, and same-day policy options are often available when you need protection quickly.
Frequently Asked Questions
Q: What is climate risk in commercial insurance?
Climate risk in commercial insurance means the chance of money loss because of weather events like storms, floods, heat waves, and power cuts. These events can damage property and stop business operations if proper coverage is not in place.
Q: Why are commercial insurance premiums increasing in 2026?
Premiums are going up because weather damage claims are happening more often and are more costly. Insurance companies adjust prices, deductibles, and rules to manage these rising costs.
Q: Does standard commercial insurance cover all climate-related damages?
Not always. Some policies do not include flooding or may limit coverage for wind or storm damage. It is important to check your policy and add extra coverage if needed.
Q: How can businesses lower climate-related insurance risks?
Businesses can reduce risk by keeping their property in good condition, adding safety systems, updating coverage, and following regular maintenance. Small improvements can help prevent bigger damage.
Q: Is business interruption insurance necessary for climate risks?
Yes, it can be very helpful. It covers lost income when your business cannot run because of events like storms, floods, or power outages. This helps keep your cash flow stable during downtime.
Climate-related risks are no longer a future concern-they are a present-day reality for businesses across Texas. From severe storms and flooding to extreme heat and power outages, climate events are changing how commercial insurance works in 2026.
At AZ Insurance, we help business owners understand how climate risk affects coverage, premiums, and protection plans - so you can stay prepared and protected.
How Climate Risk Is Changing Commercial Insurance
Insurance companies are changing policies as weather-related claims continue to rise. Businesses are seeing changes such as:
Higher deductibles for weather-related losses
Higher premiums in high-risk areas
Stricter approval rules for coverage
More focus on risk prevention steps
This makes understanding climate risk commercial insurance more important than ever for business owners. Our team is here to help with understanding coverage options and risk planning.
Common Climate-Related Risks Facing Texas Businesses
Texas businesses are especially exposed to climate-related events, including:
🌪 Severe Storms & Wind Damage
Strong winds and hail can damage roofs, signs, and equipment.
🌊 Flooding
Even businesses outside flood zones can face water damage from heavy rain.
🔥 Extreme Heat
Heat waves can lead to equipment breakdown, power issues, and employee safety problems.
⚡ Power Outages
Weather-related outages can stop business operations and cause loss of income.
Without proper coverage, these events can lead to high out-of-pocket costs.
Why Commercial Insurance Coverage Matters More in 2026
The right Texas commercial insurance policy can help protect your business from climate-related losses, including:
Business Interruption Insurance – Helps cover lost income when your business is temporarily closed
Commercial Auto Insurance – Covers damage to business vehicles caused by weather
General Liability Insurance – Protects against claims from third-party property damage
Good coverage helps your business recover faster after unexpected events.
Steps Business Owners Can Take to Reduce Risk
Insurance is only one part of the protection. Businesses can also lower risk by:
Reviewing insurance policies every year
Updating property and equipment values
Following regular safety and maintenance checks
Adding protection systems like drainage, surge protection, and strong roofing
Taking these steps can also help control insurance costs over time.
How to Review Your Policy for Climate Risk
Many businesses think they are fully covered until they face a claim. Reviewing your policy can help you avoid surprises.
Check if flood, wind, or power outage damage is included
Make sure coverage limits match your current property value
See if business interruption coverage includes weather-related closures
Ask your insurer about extra coverage options if needed
A simple review now can prevent big losses later.
Why Businesses Trust AZ Insurance
AZ Insurance has been supporting local businesses and families for years with simple, reliable coverage and real guidance when it matters most. With multiple local offices across Houston, help is always close by when you need it.
Our licensed agents speak multiple languages, so you can get clear answers without confusion. You also deal directly with real people—not automated call centers—so you always get personal support.
We’ve helped thousands of customers find the right coverage, and same-day policy options are often available when you need protection quickly.
Frequently Asked Questions
Q: What is climate risk in commercial insurance?
Climate risk in commercial insurance means the chance of money loss because of weather events like storms, floods, heat waves, and power cuts. These events can damage property and stop business operations if proper coverage is not in place.
Q: Why are commercial insurance premiums increasing in 2026?
Premiums are going up because weather damage claims are happening more often and are more costly. Insurance companies adjust prices, deductibles, and rules to manage these rising costs.
Q: Does standard commercial insurance cover all climate-related damages?
Not always. Some policies do not include flooding or may limit coverage for wind or storm damage. It is important to check your policy and add extra coverage if needed.
Q: How can businesses lower climate-related insurance risks?
Businesses can reduce risk by keeping their property in good condition, adding safety systems, updating coverage, and following regular maintenance. Small improvements can help prevent bigger damage.
Q: Is business interruption insurance necessary for climate risks?
Yes, it can be very helpful. It covers lost income when your business cannot run because of events like storms, floods, or power outages. This helps keep your cash flow stable during downtime.
Latest Blogs

SR-22 Baytown TX: Get It Filed Same Day After a Suspension

Is Texas Minimum Car Insurance Enough? What 30/60/25 Actually Pays After a Crash

Texas SR-22 After a DWI: How to Reinstate Your License

Hit by an Uninsured Driver in Texas? The Coverage You May Have Turned Down Without Knowing

How Much Does Umbrella Insurance Cost in Texas?

Does Homeowners Insurance Cover Foundation Damage in Texas? What Pays, What Does Not, and the Endorsement to Ask For
Let A-Z Auto Insurance Help You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto
Insurance Help You
Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Let A-Z Auto Insurance Help
You Find Affordable Coverage
Connect with our experienced team today & get reliable, affordable insurance designed around your needs.
Contact Us!
Latest New & Blogs
Latest New & Blogs
Related Blog Posts
Related Blog Posts
Texas SR-22 After a DWI: How to Reinstate Your License
Need a Texas SR-22 after a DWI? Learn the steps, costs, and 2-year timeline to reinstate your license, avoid a costly lapse, and get your quote today.
Texas SR-22 After a DWI: How to Reinstate Your License
Need a Texas SR-22 after a DWI? Learn the steps, costs, and 2-year timeline to reinstate your license, avoid a costly lapse, and get your quote today.
Texas SR-22 After a DWI: How to Reinstate Your License
Need a Texas SR-22 after a DWI? Learn the steps, costs, and 2-year timeline to reinstate your license, avoid a costly lapse, and get your quote today.
Hit by an Uninsured Driver in Texas? The Coverage You May Have Turned Down Without Knowing
About 1 in 8 Texas drivers is uninsured. UM/UIM and PIP are on every Texas policy unless someone rejected them in writing. Here is how to check yours.
Hit by an Uninsured Driver in Texas? The Coverage You May Have Turned Down Without Knowing
About 1 in 8 Texas drivers is uninsured. UM/UIM and PIP are on every Texas policy unless someone rejected them in writing. Here is how to check yours.
Hit by an Uninsured Driver in Texas? The Coverage You May Have Turned Down Without Knowing
About 1 in 8 Texas drivers is uninsured. UM/UIM and PIP are on every Texas policy unless someone rejected them in writing. Here is how to check yours.
How Much Does Umbrella Insurance Cost in Texas?
How much does an umbrella policy cost? See average umbrella insurance rates by limit, what drives the price, and how Texans can save. Get a quote today.
How Much Does Umbrella Insurance Cost in Texas?
How much does an umbrella policy cost? See average umbrella insurance rates by limit, what drives the price, and how Texans can save. Get a quote today.
How Much Does Umbrella Insurance Cost in Texas?
How much does an umbrella policy cost? See average umbrella insurance rates by limit, what drives the price, and how Texans can save. Get a quote today.
Texas SR-22 After a DWI: How to Reinstate Your License
Need a Texas SR-22 after a DWI? Learn the steps, costs, and 2-year timeline to reinstate your license, avoid a costly lapse, and get your quote today.
Hit by an Uninsured Driver in Texas? The Coverage You May Have Turned Down Without Knowing
About 1 in 8 Texas drivers is uninsured. UM/UIM and PIP are on every Texas policy unless someone rejected them in writing. Here is how to check yours.